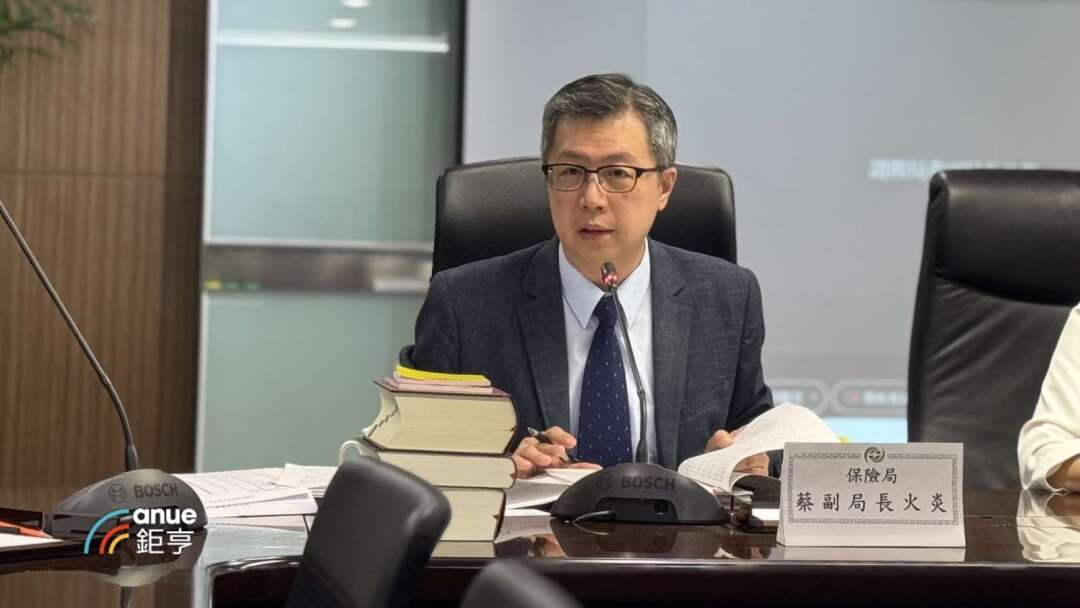
The Financial Supervisory Commission (FSC) today (24th) approved disciplinary action against Taiwan Life Insurance, citing serious deficiencies in its internal control system. An employee had been misappropriating suspense account funds for five consecutive years, with the total amount involved exceeding NT$16.53 million. The FSC confirmed clear violations of regulations and imposed a heavy fine of NT$9.6 million on Taiwan Life under the Insurance Act and Anti-Money Laundering Act—setting the highest penalty record for the insurance industry this year and marking the first known case of suspense account misuse.
Insurance Bureau Deputy Director Tsai Huo-Yen explained that the case originated from customer complaints about not receiving surrender refunds from lapsed policies. After internal investigations revealed anomalies, Taiwan Life reported the incident as a major unexpected event to the FSC on December 1, 2025. However, since the FSC was already conducting a routine business inspection, it immediately expanded the review into a full financial audit.
Tsai pointed out that the implicated employee, Ms. Yang, used a 'robbing Peter to pay Paul' method, exploiting loopholes in the company’s internal controls to privately refund 94 payments to specific third parties unrelated to the policies—namely, her relatives.
The FSC listed Taiwan Life's main violations: First, refund approvals were merely formalities. Ms. Yang could approve refunds without attaching payment vouchers or authorization forms, and related transaction records were not properly archived, making it impossible to reconstruct the events later.
Second, job duties were not strictly separated. Some reviewers shared their account passwords with others; initiators even held disbursement approval rights in another system. The system also failed to restrict the same person from handling both original suspense entries and automatic premium offset cancellations, eliminating internal checks and balances.
Third, the system lacked control mechanisms. Staff could unilaterally modify repayment dates in the system without authorization, zeroing out late fees and booking them as regular premiums. Moreover, no monitoring or evaluation mechanisms existed for abnormal behaviors such as automatic offset transfers, changing payees to third parties, or splitting one suspense item into multiple payments.
Fourth, anti-money laundering safeguards were inadequate. During abnormal refund operations, the company failed to conduct mandatory name and entity screening of transaction counterparts.
Fifth, management of lapsed policies was lax. Refundable amounts from foreign currency lapsed policies without bank accounts were not included in follow-up contact mechanisms, remaining as suspense items for extended periods and thus vulnerable to employee misuse.
The FSC stated the total penalty amounted to NT$9.6 million: NT$8.4 million for internal control and anti-money laundering deficiencies, and an additional NT$1.2 million for improper handling of refundable amounts from lapsed policies.
Tsai emphasized that the penalty level was determined after thorough internal deliberation, considering the five-year duration of fraud (May 2020 to June 2025), the large sum involved, and the breach of multiple core operations—constituting a major internal control failure. This marks the FSC’s first penalty specifically targeting 'suspense account internal control deficiencies' in the insurance industry.
Regarding affected policyholders’ rights, Taiwan Life has completed comprehensive remediation, absorbing all losses at its own expense, and will pursue recovery from the responsible employee.
The FSC also requires Taiwan Life to immediately audit all current suspense accounts, hold senior executives and negligent personnel accountable based on a 'responsibility map,' and submit a corrective improvement plan. The FSC particularly urges that integrity is the cornerstone of insurance operations. Financial institutions must not simply attribute fraud to 'individual employee misconduct.' Boards and senior management must earnestly fulfill supervisory responsibilities and strengthen organizational integrity culture.
FACT BOX
- Source: PR Times
- Category: News